
Most merchant cash advance declines come down to a handful of reasons: revenue below the minimum, too little time in business, deposits that are inconsistent, open advances that were not disclosed or that the business cannot carry, incomplete or unreadable statements, a restricted industry, or asking for more than the deposits support. Most of them can be spotted before you apply.
Here is each reason as Legend Advance Funding applies it, and what you can work on before you apply again. Fixing these improves a file. It does not guarantee an approval.
1. Monthly Revenue Below the Minimum
Our minimum is $20,000 in monthly revenue. If your deposits fall below that, the file does not meet the baseline.
What to work on: run all business revenue, including card settlements and cash deposits, through the business checking account you apply with, so your statements show your full volume.
2. Inconsistent Deposits
Consistency matters as much as the total. Steady month-over-month deposits make a stronger file than one strong month next to several weak ones. Underwriting reviews deposit consistency on every file.
What to work on: send the full set of statements requested, not just your best months. If your business is seasonal, the full pattern is what underwriting needs to see. Our guide to seasonal business funding covers how to plan around uneven months.
3. Less Than 3 Months in Business
We require at least 3 months in business. Underwriting reads deposit history, so a business without 3 months of activity in its account does not have enough history to review.
What to work on: wait until you have at least 3 months of revenue running through an active US business checking account.
4. No Active US Business Checking Account
An active US business checking account is required. Applying with a personal account, or an account that does not carry your business revenue, does not meet the baseline.
What to work on: open and use a business checking account for your business deposits before you apply.
5. Open Advances That Were Not Disclosed
We review existing advances case by case, and in some cases we can consolidate or fund alongside an existing position. Full disclosure is required. An undisclosed advance found during verification will stop a file.
What to work on: list every open advance on your application, with the current remittance and remaining balance.
6. Existing Advances Your Deposits Cannot Carry
When you already have an open advance, underwriting looks at your current remittance amounts, remaining balances and total capacity against your actual deposits. If your deposits cannot carry another remittance, we will tell you rather than fund a position your business cannot support.
What to work on: if your current remittances already take a large share of your deposits, wait until a position is closer to complete, or ask about consolidation when you apply.
7. Incomplete, Illegible or Partial Bank Statements
Missing pages, partial statements and unreadable files are among the most common causes of a stalled or declined file. Underwriting cannot approve what it cannot read.
What to work on: send complete statements with every page, as clear PDFs, along with the other documents on our merchant cash advance document checklist.
8. A Restricted Industry
We do not fund gambling, adult entertainment or illegal services. Files in these categories cannot be funded regardless of revenue strength.
What to work on: nothing on the application changes this. If you are not sure whether your industry qualifies, contact us before applying.
9. Asking for More Than Your Deposits Support
Requesting a realistic amount against your actual revenue is the single biggest factor in whether a file is approved. The amount we can offer depends mainly on your average monthly deposits, time in business, industry and existing obligations.
What to work on: request an amount you can show your revenue supports, and size it to the specific need rather than the maximum.
What Is Not a Reason on Its Own: Your Credit Score
Credit is one input, not the deciding factor. We have no strict minimum FICO for most programs and weigh business performance and cash-flow stability above the personal score. Strong, consistent deposits can offset a lower credit profile. The initial application uses a soft credit pull, so applying does not affect your credit score; full verification happens only after an offer is accepted.
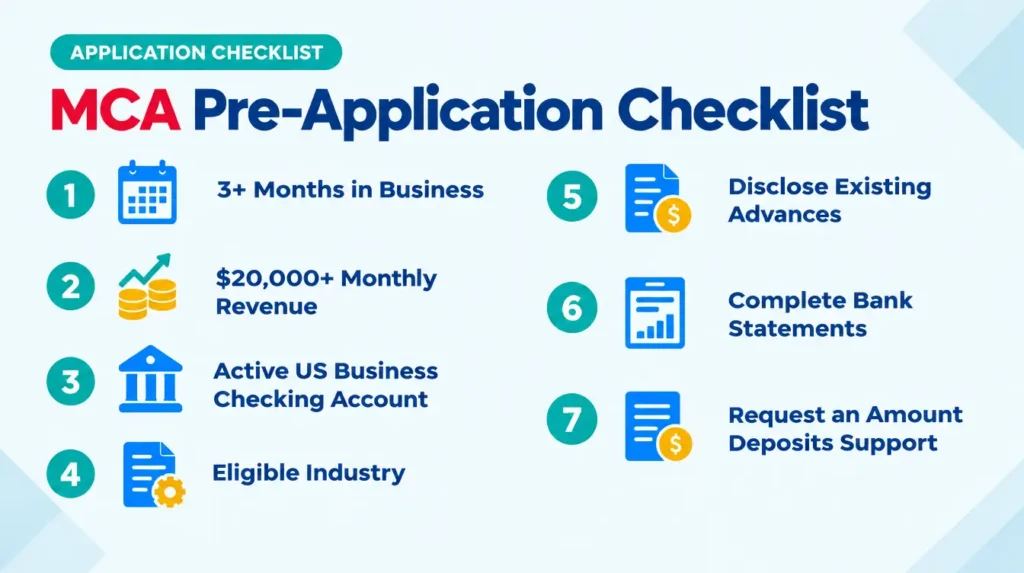
Quick Pre-Application Checklist
| Check | Our baseline |
| Time in business | 3 months or more |
| Monthly revenue | $20,000 or more, consistent month to month |
| Bank account | Active US business checking account |
| Industry | Not gambling, adult entertainment or illegal services |
| Existing advances | All disclosed, with remittances your deposits can carry |
| Statements | Last 3 to 6 months, every page, readable |
| Amount requested | Supported by your actual deposits |
You can see the full criteria on our program guidelines page.
If You Were Declined
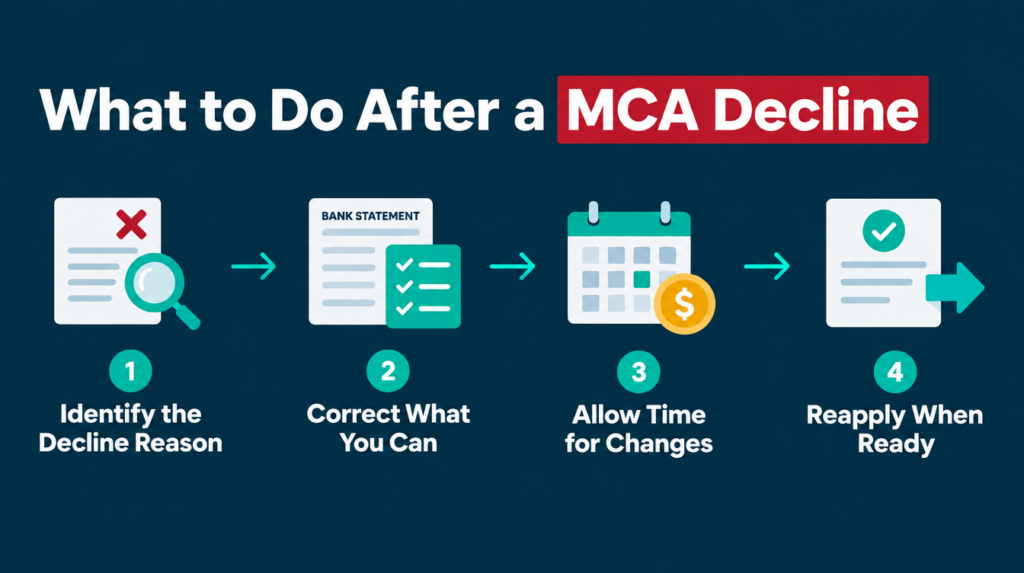
- Find out which reason applied.
- Fix what you can: statements, disclosure, account setup, or the amount you ask for.
- Give time-based reasons time: 3 months in business, a steadier deposit history, or an existing position that is further along.
- Apply again when the file reflects the change.
If it was a bank, not an MCA provider, that turned you down, read where to go when banks say no.
Ready to Apply?
If your business meets the baseline, see what you qualify for. Applying takes about five minutes, and decisions generally come within 24 hours of a complete application.
Check My Merchant Funding Options
All funding is subject to underwriting, verification and approval. Available to US businesses only.